For much of the past decade, blockchain technology has been closely associated with cryptocurrencies and speculative investing. But behind the headlines, a quieter transformation is taking place within the financial industry. Banks, asset managers, and providers of market infrastructure are increasingly focused on tokenization, a technology that could change how financial assets are issued, traded, and managed.
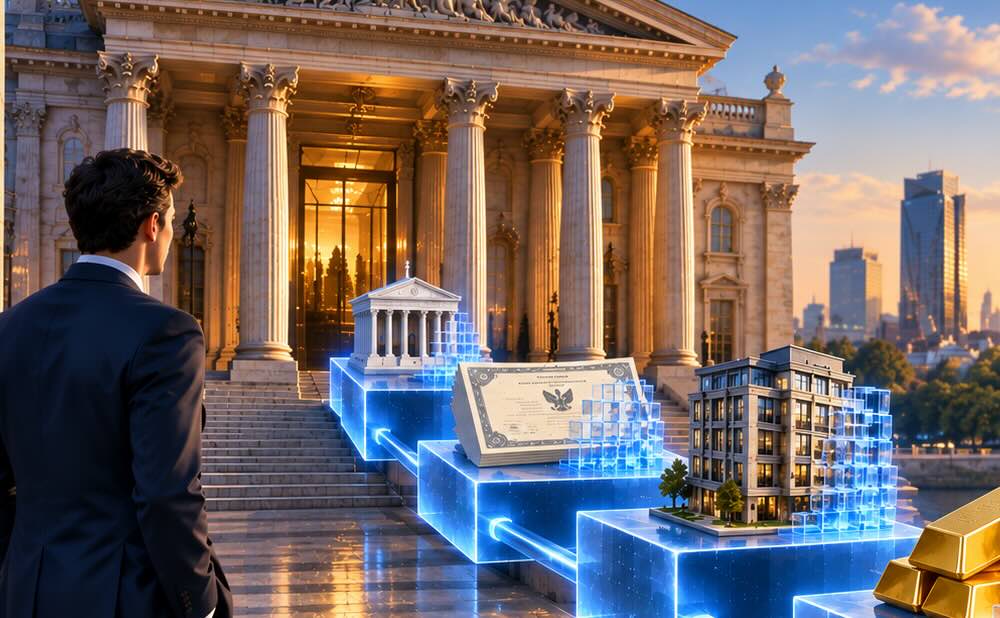
Tokenization is the process of creating a digital representation of ownership in a real-world asset. Digital tokens could represent ownership in government bonds, money market funds, private equity, real estate, commodities, or even fine art. Crucially, tokenization does not change the underlying asset. It changes the infrastructure used to record and transfer ownership.
Tokenization is useful because today’s financial system depends on a complex network of brokers, custodians, clearing houses, and settlement systems. Each participant maintains its own records, requiring continuous reconciliation between institutions. Although the old infrastructure has supported global markets for decades, its limitations have long been tolerated for want of a better solution.
Tokenization could simplify parts of the process. By recording ownership on a blockchain, a kind of decentralized ledger, authorized participants will be able to access a single source of truth. Transactions that currently require three business days to settle could be completed within minutes or even seconds. Faster settlement has the potential to reduce counterparty risk, increase liquidity, and lower transaction costs.
Tokens could also be programmable, allowing smart contracts to be automatically executed when specified conditions are met. Interest payments, dividend distributions, and compliance checks could all be automated. By setting up rules that determine when future transactions occur, financial institutions will be able to reduce human error and improve auditability. This can also enable them to reduce labour costs or redeploy staff to deliver more value to customers.
Tokenization could also broaden access to some investment products. Private assets have traditionally required large minimum commitments because ownership interests are costly to divide, transfer, and administer. Tokenization can make it easier to issue small ownership stakes and maintain accurate records. Regulation will still determine who can invest in particular financial products, but the technology can lower some of the barriers that have traditionally limited participation.
The potential of tokenization helps to explain why many of the world’s largest financial institutions are betting heavily in this space. JPMorgan has developed a blockchain-based payment and settlement solution for institutional clients. BlackRock has launched a tokenized money market fund, while Franklin Templeton now offers a U.S. registered mutual fund that records transactions using blockchain technology. These initiatives indicate that tokenization is moving beyond the beta-testing experimentation phase and becoming part of mainstream financial infrastructure.
One important caveat is that tokenization does not solve every problem in the financial markets. An asset does not automatically become more valuable or liquid simply because it is tokenized. The economic fundamentals remain unchanged. A commercial building, private company, or government bond carries the same underlying investment risks regardless of how ownership is recorded. Tokenization can improve market efficiency, but it cannot eliminate key investment risks or create demand for worthless assets where none exists.
A second constraint is institutional rather than technical. Clear legal and regulatory frameworks are needed to establish ownership rights, digital ID, and interoperability between platforms. Without common standards, tokenization could simply replace today’s fragmented infrastructure with multiple blockchain-based silos that cannot communicate effectively with one another.
This is why organizations such as the Bank for International Settlements and the International Monetary Fund have argued that tokenization has the potential to improve the architecture of the global financial system if implemented responsibly. Their reports argue that programmable assets and tokenized forms of money could support more efficient global financial markets as well as enhance the kind of regulatory oversight required in modern financial systems.
For business leaders, the most useful way to view tokenization is as an innovation in financial infrastructure rather than as a crypto trend. Much like cloud computing modernized enterprise technology without changing the core purpose of businesses, tokenization has the potential to modernize the systems that support financial markets. The key question is not whether every asset should be tokenized, but whether decentralized ledgers, programmability, and faster settlement can remove barriers and friction points. Companies that begin testing practical use cases today will be in a better position to benefit as digital asset infrastructure matures.
Mohammad Khan is a finance and technology professional who has built digital products on Wall Street.
Image: DALL-E
🔴 Found these ideas useful?
Sharpen your edge